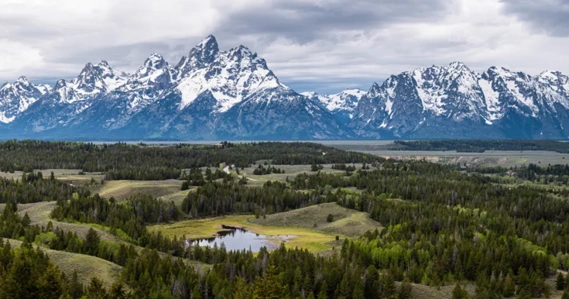
At the end of August, the world’s central bank leaders gathered in the Rocky Mountains as guests of the Federal Reserve Bank of Kansas City. The Jackson Hole Economic Policy Symposium, held this year from 27 to 29 August and hosted by Kansas City Fed President Jeffrey Schmid, is — alongside the IMF and World Bank Annual Meetings — one of the fixed points in the year for insight into what the world’s monetary policy leaders are thinking. The academic papers are of the highest level, and the venue is inspiring and tranquil for quiet conversations.
This article is meant to summarize the considerable content presented. The footnote below guides readers to this information source. The agenda and the public documentation are fundamental matters for finance everywhere, because this is how central bankers communicate. If it seems very high level, it is; nothing is more “macro” than global central bankers’ discussions.
Inflation has been running above the central bankers’ own targets for several years, and the question of imminent interest rate increases was very much in the air. This year it was also the public focus. In his keynote address, “In Our Time,” Federal Reserve Chairman Kevin Warsh put PCE inflation at 3.7 percent over twelve months and 4.1 percent over six, described progress over the past two years as modest, and observed that about half the goods and services in the PCE basket had risen at annualized rates above 3 percent. His conclusion was blunt: the Fed “must be confident that underlying inflation is moving to our objective, clearly and at sufficient speed. Otherwise, we have work to do.” He declined to give rate guidance, committing instead to “a discipline, not to a decision,” and argued that conventional forward guidance has become counterproductive in normal times. Markets read the speech as raising the odds of a near-term increase ahead of the September meeting. European Central Bank voices leaned the same way; Bank of England Governor Andrew Bailey was more cautious, pointing to subdued second-round effects and a softening labor market.
The other topic the press had expected — sovereign debt piled as high as the mountains behind the delegates — stayed off the formal agenda, but it was not absent. In the luncheon address, Kenneth Rogoff of Harvard University argued that the United States is heading toward a debt reckoning, and that it will probably take an economic shock to force action on the deficit.
This year’s theme was “Financial Innovation — Implications for Payments and Policy.” Friday’s sessions were chaired by Kristin J. Forbes of MIT and Saturday’s by Anil Kashyap of the University of Chicago. The theme was examined from several angles, as presented here:
Financial Innovation and the International Monetary System
The paper, by Eswar Prasad of Cornell University with Catherine L. Mann of the Bank of England as discussant, pushes back on the assumption that dollar dominance is quietly ending. The safe asset status of the currency and US Treasuries is indeed being questioned: the convenience yield on Treasuries has fallen and turns negative at longer maturities, and the dollar’s share of global foreign exchange reserves has slipped from 72 percent in 2000 to 57 percent in the first quarter of 2026. These shifts are the logical results of macroeconomic policy, the erosion of supporting institutions, and the weaponization of the currency. Yet the dollar still accounts for 59 percent of cross-border payments, 82 percent of trade finance, and 90 percent of foreign exchange turnover. No challenger has emerged, because the major reserve currencies are faring little better than the dollar, while the smaller ones are too small to carry the burden.
The more striking argument concerns what financial innovation does to this picture. Rather than leveling the playing field, digitalization may intensify the dollar’s network effects: stablecoins and tokenized money make dollar assets easier to acquire and hold, which draws in more dollar borrowing, which deepens dollar markets further: “issuance begets issuance.” Meanwhile the renminbi’s internationalization has stalled, its share of global reserves peaking near 3 percent in 2022 and falling to about 2 percent by early 2026. What has grown is the collective weight of the smaller currencies —the Canadian and Australian dollars, the Swiss franc, the Swedish krona and their peers — rather than any single alternative. The perceived strength of the euro, yen, and sterling has weakened somewhat over the same period. Emerging market central banks, for their part, largely stopped accumulating reserves after 2015; it is private sector actors in those countries who now drive foreign asset purchases, and they are the more sensitive to anything that reduces friction in cross-border investment.
Prasad sets out three possible outcomes for currency usage in global affairs. There might be greater concentration still in the top few currencies, with more fragmentation in the second tier. Or the world may evolve toward a balanced multipolarity, supported by strong institutions and regulation and backed by deep and liquid markets. Or, finally, the outcome could be outright currency and financial fragmentation built on shaky foundations, in which competition produces destabilizing capital flows, herding, and financial cascades. He does not leave the three evenly weighted: on present trajectories, he judges, the first outcome appears the most likely, with a nontrivial probability of the third. Multipolarity is desirable in principle, but only if it rests on strong foundations.
Tokenized Finance
The session’s paper, “Tokenized Finance and the Perimeter of Central Banking” by Darrell Duffie of Stanford University, argued that financial market activities and record-keeping will eventually move to 24/7 programmable ledgers, the near-term appeal lying in improved collateral mobility: cash collateral for around-the-clock repo, and derivatives margin. To maintain financial stability, core market settlement will have to be in central bank money; stablecoins and tokenized commercial bank deposits are not suited to systemically critical uses. Central banks might expect that during the transition, fragmentation between legacy payment systems and new ledgers will raise the aggregate demand for settlement balances and so increase central bank balance sheets. At the end of this transition period, when central bank money is tokenized, the reserves held against the risk of settlement failure should decline.
The discussant, Isabel Schnabel of the European Central Bank, agreed that this could work on two conditions: settlement in central bank money can be automatic, with the stipulated conditions programmed into the ledger, and all legs of the transaction must settle at once or not at all. She went further than the paper in one respect, arguing that central banks should bring their money onto programmable ledgers themselves rather than work through intermediaries, and framing stablecoins as complements to central bank reserves rather than substitutes for them.
Payments
This session was a panel on international experience with payments innovation, with Pablo Hernández de Cos of the Bank for International Settlements, Stefano Scarpetta of the OECD, and Kristalina Georgieva of the International Monetary Fund. Hernández de Cos contrasted stablecoins with tokenized deposits (commercial bank money on a ledger) assessing both against three criteria: singleness, meaning that one form of money is interchangeable with another; interoperability across networks; and integrity and accountability. He concluded that tokenized deposits should carry bulk payments and wholesale settlement, with stablecoins confined to narrower roles under strict regulatory oversight. For central bankers, adoption of ledgers is a more direct way to advance while preserving the monetary system’s foundations. It also better matches market realities, because in any transition there must be coexistence with — and migration from — legacy systems, a period in which all actors are best kept under supervisory oversight. Georgieva’s summary of the problem being solved was characteristically direct: cross-border transactions are “still too costly and too slow.”
For now, no interoperable multi-bank or cross-border system exists. Central bank digital currency pilot programs are mostly permissioned, or in some way imitate stablecoins, and neither approach meets the need. The key challenges are developing ledgers that allow for interoperability, competition, and inclusion. There is also a governance problem for central bankers to resolve among themselves, because payments require legal clarity and operational resilience.
Banking
The paper, “Financial Innovation and the Future of Banking” by Christine A. Parlour of the University of California, Berkeley, with Itay Goldstein of the Wharton School as discussant, set out a formal analysis of stablecoins as an alternative to today’s bank-based accounts. Stablecoins have emerged as a leading application of fintech with the potential to be used as money. Will this eventually crowd out the banking system itself?
Stablecoins present technology benefits that can help overcome friction in current payment systems. Their use is growing in volume but remains limited.
A key drawback is that stablecoins generate no information about creditworthiness, which bank account-based finance does. As payments migrate away from bank accounts, that information is lost and funds move toward less regulated nonbank intermediaries, which is where Parlour locates the systemic risk. The paper leaves a set of open questions. What would be the response of banks to both more stablecoins and the role of tokenized deposits? What can central banks and policymakers learn from market-based intermediaries and their liquidity transformation? What information structure would emerge in the era of new technologies? What are the other risks inherent in widespread adoption of stablecoins?
AI and the Future of Finance
The paper under this heading, “Artificial Intelligence and the Brave New World in Finance” by Markus K. Brunnermeier of Princeton University, with Raghuram G. Rajan of the University of Chicago as discussant, was the most unsettling of the symposium. Information is the fuel of finance, and in 2026 all financial actors are being affected by generative AI, which by definition is about information.
Economics assumes that even when people know different things, they have a common general understanding and can describe the world to one another in a shared language. Is this about to be disrupted?
Trust in the understanding of experts, extended by institutions, gives each person access to a broad societal understanding. The introduction of agentic AI is qualitatively different from previous innovations, which were neither strategic nor deceptive. It disrupts the trust arrangement and undermines societal understanding: AI agents can learn how humans think and respond, while humans may be unable to understand or reliably anticipate how those agents will act. This asymmetry can make prices harder to read (less informationally efficient) and put central banks at a strategic disadvantage when engaging and communicating with market participants. Preparing for the asymmetric understanding scenario calls for segmented markets that preserve a human fallback, human authorization above defined thresholds, and simpler, blunter central bank rules that acknowledge the limits of what the regulator can read. It also calls for retiring constructive ambiguity: once AI can extract hidden rules from observed behavior, the only robust substitute is genuine randomization within publicly announced bounds.
Central Banking
The closing panel considered financial innovation from the central banking side, with Wenxin Du of Harvard Business School, Arvind Krishnamurthy of Stanford University, and Jesús Fernández-Villaverde of the University of Pennsylvania. Du’s remarks, titled “Three Myths About Payment Innovation,” took on three widely held propositions:
1. 24/7 atomic real-time gross settlement is the future of wholesale payments.
2. Retail payment frictions are mainly a legacy technology problem.
3. Stablecoins are efficient for cross-border payments.
In each case, Du argued, the claim focuses on the visible payment rail while overlooking the economic architecture around it. Payment innovations are often judged by what is easiest to see: whether a system operates around the clock, whether settlement is instant, and whether its ledger is built on a blockchain of some kind. But progress in payments involves much more than moving a token quickly. It also requires, in her words, “managing liquidity and risk, complying with regulation, resolving errors and disputes, and earning users’ trust.” Her example is pointed: CLS achieves roughly 96 percent netting efficiency in foreign exchange settlement, a saving that pure real-time gross settlement would simply give up.
That distinction between what the technology makes possible and what institutions, incentives, and trust actually deliver ran through all three days of discussion.
Notes
https://www.kansascityfed.org/research/jackson-hole-economic-symposium/2026/. The papers presented by discussants are linked to this site, and in those presentations there are links to detailed research.
The articles published here reflect the views of the respective authors and not necessarily those of the WAIFC.